We have improved our order execution system for the following instruments:
- GOLD (xyz:GOLD)
- SILVER (xyz:SILVER)
- SP500 (xyz:SP500)
- XYZ100 (xyz:XYZ100)
- CL (xyz:CL)
- BRENTOIL (xyz:BRENTOIL)
Previously, market orders on these instruments used a simulated fill algorithm that walked through multiple order book levels on Hyperliquid to determine execution prices.
Starting today, orders are filled at the top-of-book price (Level 1) with a transparent, size-based slippage model that reflects real-world CME execution costs.
Slippage is applied based on your order's notional value.
For example, for XYZ100 (xyz:XYZ100):
Up to $100,000, 0.09 bps
Up to $200,000, 0.1 bps
Up to $1,000,000, 0.12 bps
Slippage is applied adverse to your order direction (buys pay slightly above market, sells receive slightly below market) to reflect realistic market impact.
This brings us closer to industrial futures pricing, without relying on Hyperliquid's book depth. Note that the spread is the same outside of regular trading hours.
Before: A $100K market buy on Gold might have walked through 3-4 book levels with varying impact.
Now: Same order fills instantly at the best bid +0.23 bps
The fill methodology and breakdown has been added on propr.xyz/universe
For algo traders, you can read the slippage config here: https://api.propr.xyz/v1/exchange-assets/config/hyperliquid


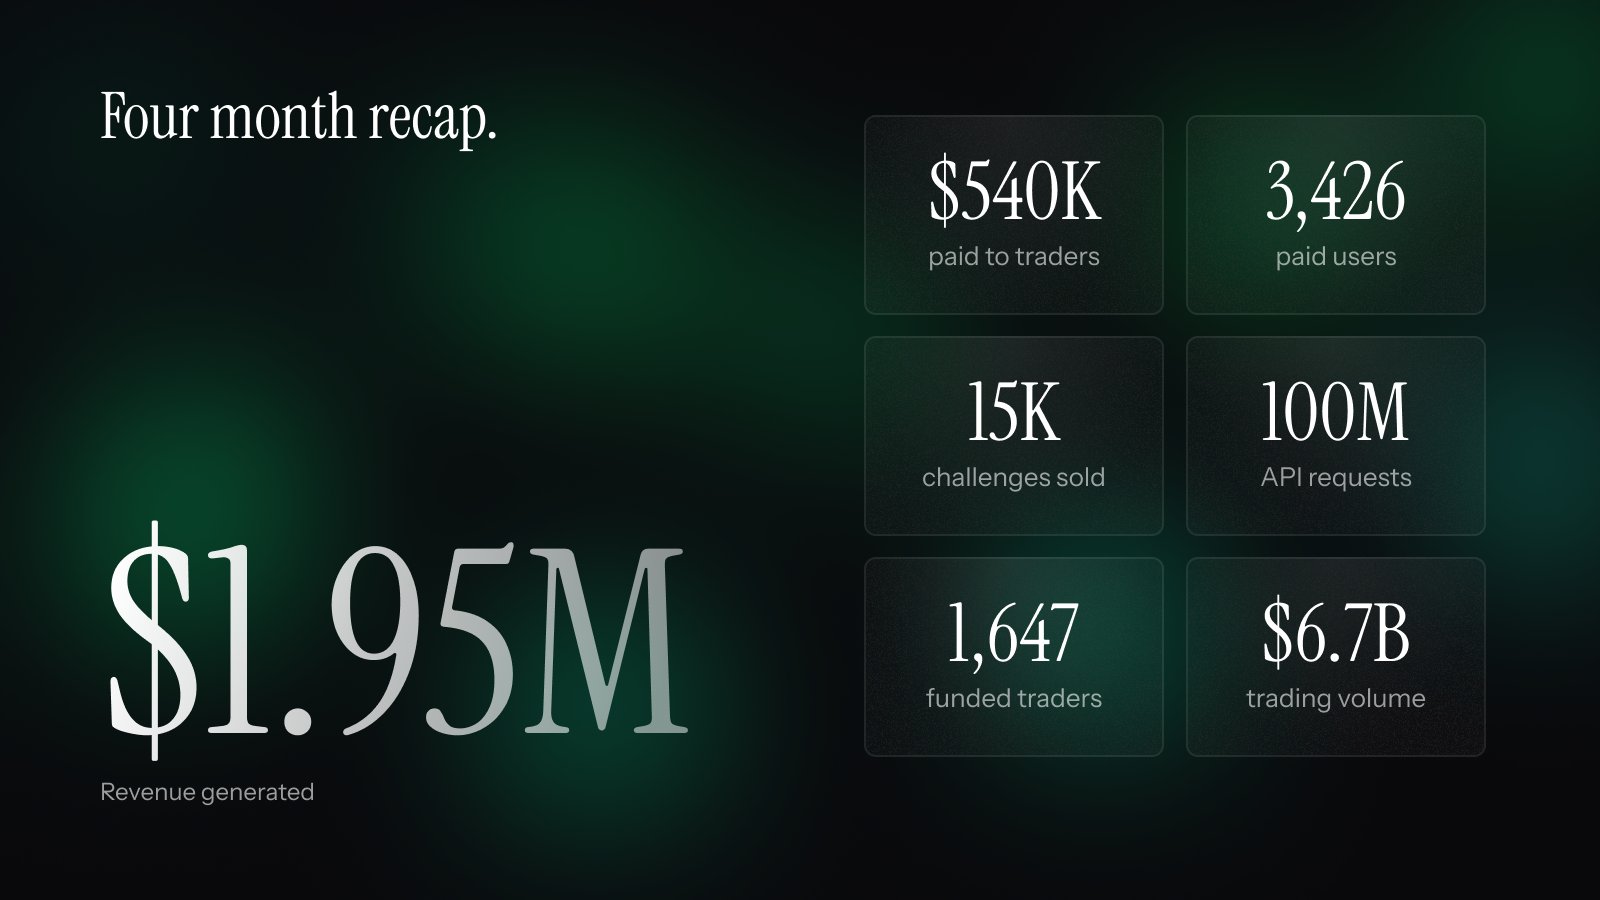
 #🎙️・ [08.12] PROPR AMA



External Link
Platform
You are about to visit:
https://example.comThis will open in a new tab. Make sure you trust this link.