Why Return Order Changes Autocorrelation
Summary
Hollow Point Trading shares an example showing how four returns of +1%, −1%, +1%, and −1% can have the same mean and histogram yet differ in serial dependence when observation order changes. The announcement explains lag-one sample autocorrelation and why sequence matters when analyzing market returns.
https://youtu.be/Z3tO4dM0fbo
The same four returns can have different serial dependence #Autocor...
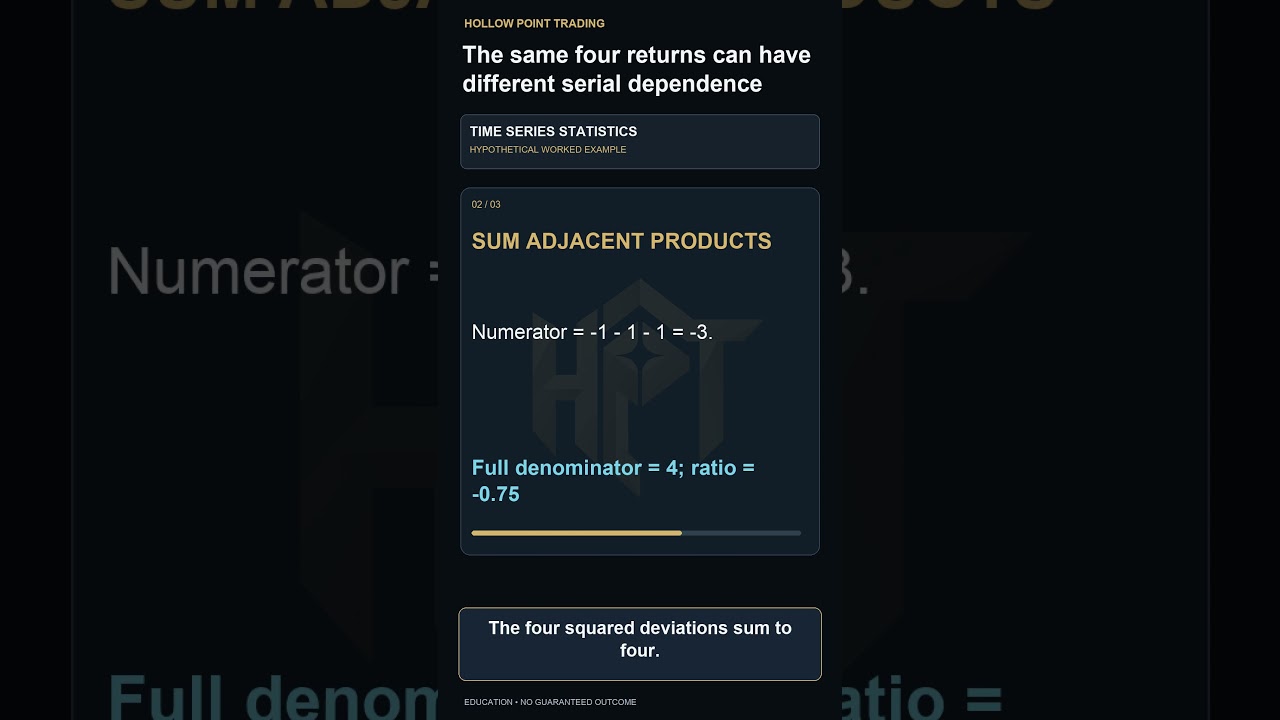
Observation order can matter even when the average and histogram stay unchanged. Consider four hypothetical equally spaced returns: plus one, minus one, plus one, minus one percent. Their mean is zero. We will use a declared lag one sample autocorrelation with the full sample squared deviation denominator. The three adjacent deviation products a...











